
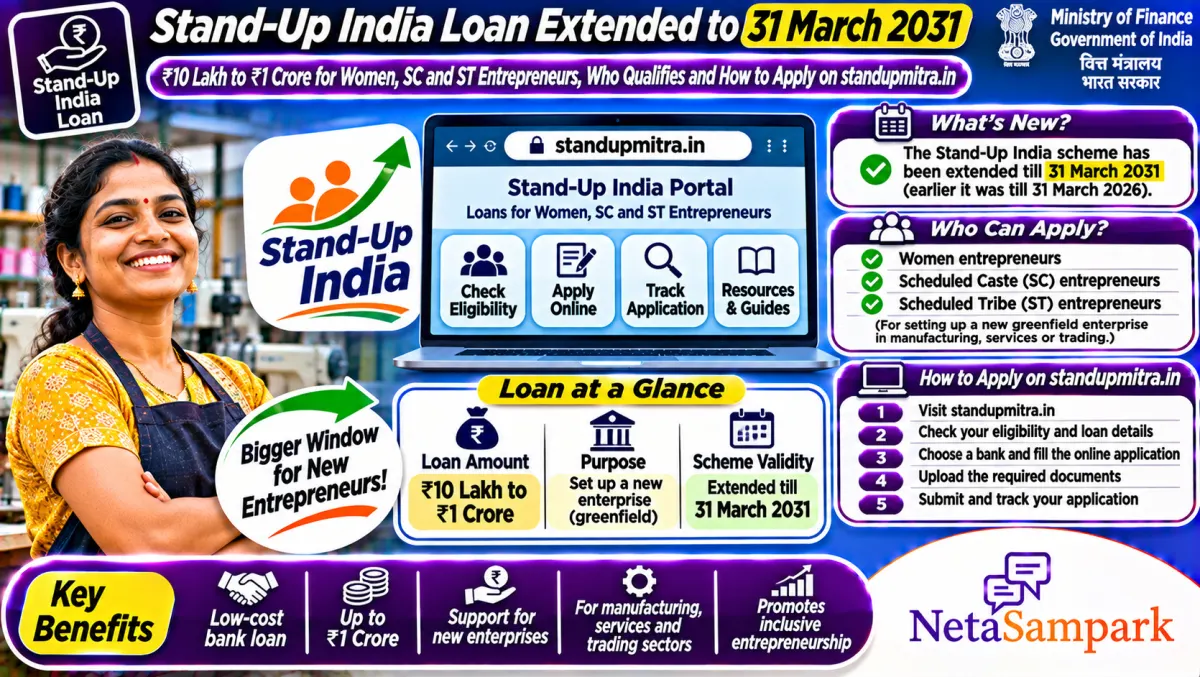
The Union Cabinet on 11 November 2026 extended Stand-Up India till 31 March 2031. Women, SC and ST entrepreneurs above 18 can get a bank loan above ₹10 lakh and up to ₹1 crore for a first-time business, covering up to 85% of the project cost. Apply on standupmitra.in or at any bank branch.
Updated 13 November 2026
If you've been planning a small factory, a clinic, a shop, a dairy unit or a service business but kept getting stuck at "how will I raise ₹20 or ₹50 lakh", this is worth a careful read. Stand-Up India isn't new. It's been running since April 2016. But the Cabinet decision on 11 November 2026 means it now runs for five more years, with a fresh ₹4,111 crore credit guarantee corpus and a target of 2.5 lakh more entrepreneurs.
Here's who can get it, how much, what the bank will ask for, and how to apply without getting bounced from branch to branch.
Quick facts
| Item | Details |
|---|---|
| Official portal | standupmitra.in (Stand-Up India portal, apply and track) |
| Helpline | Lead District Manager (LDM) help centres and handholding agencies listed on standupmitra.in, plus your bank branch |
| Fee | No fee to apply on the portal. The credit guarantee fee is 0.50%, as per the Cabinet note |
| Deadline | Scheme now runs till 31 March 2031. No closing date for applications |
| Documents | Aadhaar, PAN, caste certificate (SC or ST), project report, address proof, bank statements, business premises papers |
| Loan size | Above ₹10 lakh and up to ₹1 crore, up to 85% of project cost |
| Repayment | Up to 7 years, with a moratorium of up to 18 months |
| Who | Women, SC and ST entrepreneurs above 18, for a greenfield (first-time) enterprise |
What did the Cabinet decide on 11 November 2026?
As per the release on the Prime Minister's website:
• Stand-Up India continues for 5 years, till 31 March 2031.
• The aim is to support 2.5 lakh more entrepreneurs in these five years.
• A credit guarantee corpus of ₹4,111 crore has been approved.
• Since April 2016, more than 2.75 lakh women, SC and ST entrepreneurs have got loans.
• The loan can be a composite loan (term loan plus working capital) or a term loan, for amounts above ₹10 lakh and up to ₹1 crore, covering up to 85% of the project cost.
• Credit guarantee cover is 85% of the loan amount, with a standard guarantee fee of 0.50%.
• Eligible sectors are manufacturing, services, trading and agri-allied activities.
Who is eligible for a Stand-Up India loan?
The scheme page on standupmitra.in lists these conditions:
• You're a woman, or from a Scheduled Caste or Scheduled Tribe, and above 18 years of age.
• The business is greenfield, which means it's your first venture in that line of manufacturing, services, trading or agri-allied activity.
• If it's a company or partnership, at least 51% of the shares and controlling stake must be with a woman, SC or ST entrepreneur.
• You aren't in default to any bank or financial institution.
So if you already run a kirana shop and want to expand it, that's usually not greenfield. But if you run a kirana shop and now want to set up a small food processing unit, that's a new activity and can qualify. Ask your bank to confirm before you spend on a project report.
How much can you borrow, and what's the interest?
| Feature | What the scheme says |
|---|---|
| Loan amount | Above ₹10 lakh, up to ₹1 crore |
| Coverage | Up to 85% of project cost |
| Your contribution | 15% margin money, which can come partly from eligible central or state schemes, but you must bring at least 10% of the project cost yourself |
| Interest | The bank's lowest rate for your rating category, capped at base rate (MCLR) plus 3% plus tenor premium |
| Security | Collateral, or cover under the Credit Guarantee Fund Scheme for Stand-Up India Loans |
| Repayment | 7 years, with up to 18 months' moratorium |
| Working capital | Up to ₹10 lakh as an overdraft, with a RuPay debit card. Above ₹10 lakh as a cash credit limit |
Here's a simple example. Say your project costs ₹40 lakh. The bank can lend up to ₹34 lakh (85%). You put in the remaining ₹6 lakh, and at least ₹4 lakh of it (10%) must be your own money. The rest can come from a state subsidy scheme if you qualify for one.
How to apply on standupmitra.in step by step
1. Open standupmitra.in. Type the address yourself and tap "Apply Here" on the home page.
2. Register. Fill in the registration form with your basic contact details and verify your mobile number.
3. Fill in your business details. Expect questions on your location, category (woman, SC or ST), the kind of business, the sector and the loan amount you need.
4. Say if you need handholding. If you've never made a project report or don't know which bank to approach, ask for help. The portal connects you to handholding agencies and LDM help centres.
5. Pick a bank. The portal shows lenders near you. You can also walk into any scheduled commercial bank branch directly.
6. Submit and note your application number. The bank gets your details and contacts you.
7. Meet the bank with your project report. The bank checks your plan, your contribution and your credit history, then sanctions or rejects.
Before you go, check your credit report. A small old default can sink the application. Our free credit report guide shows how to pull it for free and fix errors.
Documents checklist
☐ Aadhaar and PAN of the promoter (and all partners or directors)
☐ Caste certificate, if applying as SC or ST
☐ Address proof for home and business premises
☐ Project report with cost, machinery quotes, sales plan and cash flow
☐ Rent agreement or ownership papers of the business premises
☐ Bank statements for the last 6 to 12 months
☐ Partnership deed or company documents, showing at least 51% with the woman, SC or ST promoter
☐ Udyam registration, if you've already done it
☐ Proof of your own contribution (bank balance or fixed deposit)
What if the bank rejects or sits on your application?
Banks are expected to give each branch at least one SC or ST borrower and one woman borrower under this scheme. So don't accept "we don't do Stand-Up India here".
1. Ask for the reason in writing.
2. Fix what you can, like a weak project report or a missing document, and reapply.
3. Contact the Lead District Manager (LDM) of your district. The LDM help centres are listed on standupmitra.in.
4. If you still get no reply in 30 days, file a complaint with the bank's grievance cell, and then with the RBI Ombudsman.
Is Stand-Up India right for you, or is Mudra better?
| You need | Look at |
|---|---|
| Up to ₹20 lakh for a small business | Mudra loan |
| Above ₹10 lakh to ₹1 crore for a new venture, and you're a woman, SC or ST | Stand-Up India |
| Toolkit and loan for traditional artisans | PM Vishwakarma |
If your business already exists and you only need working capital, a regular MSME loan may fit better. The MSME Amendment Act explainer covers what changed for small businesses this year.
Frequently asked questions
Has Stand-Up India been extended?
Yes. The Union Cabinet on 11 November 2026 approved continuing the scheme for 5 years, till 31 March 2031, with a ₹4,111 crore credit guarantee corpus.
What is the Stand-Up India loan amount?
The loan is above ₹10 lakh and up to ₹1 crore, covering up to 85% of the project cost. It can be a composite loan (term loan plus working capital) or a term loan.
Can men apply for Stand-Up India?
Only if they're from a Scheduled Caste or Scheduled Tribe. Otherwise, the loan is for women entrepreneurs. In companies or partnerships, 51% must be held by a woman, SC or ST entrepreneur.
Is collateral needed for a Stand-Up India loan?
The loan can be secured by collateral or by a guarantee under the Credit Guarantee Fund Scheme for Stand-Up India Loans, as the bank decides. Ask your bank which it will use.
How long do I get to repay?
Up to 7 years, with a moratorium of up to 18 months, as per the scheme details on standupmitra.in.
Final reminder
Before you apply, write down your project cost, keep at least 10% of it ready from your own savings, pull your credit report and fix any errors. Then register on standupmitra.in and ask for handholding if you need it. If a branch keeps refusing to process your file without reason, go to the LDM, and you can also find your MP on NetaSampark to write to their office about it.
Sources
• Cabinet approves continuation of Stand-Up India Scheme, PM India, 11 November 2026
• Stand-Up India portal (SIDBI)
• Stand-Up India scheme features