
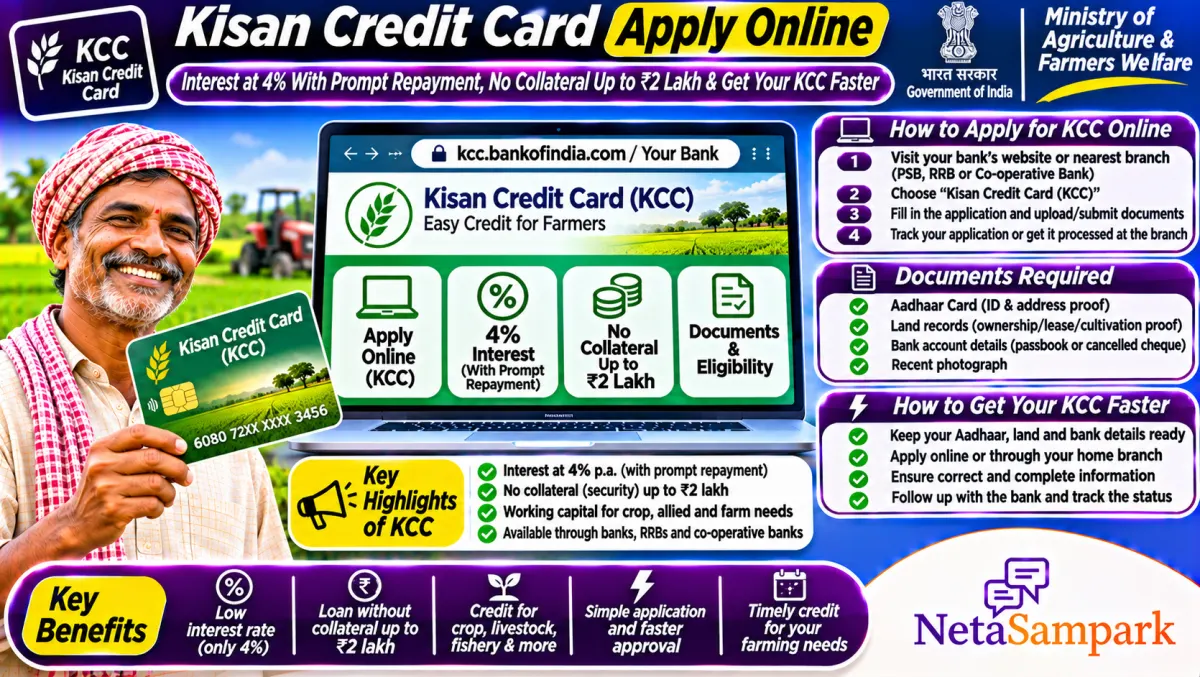
A Kisan Credit Card gives farmers a crop loan limit at 7% interest, which drops to an effective 4% if you repay on time. Loans up to ₹2 lakh need no collateral. Apply at your bank, its app or Jan Samarth, with Aadhaar, land records and a photo. PM-Kisan farmers can use a simple one-page form.
Updated 11 November 2026
Every sowing season, farmers end up borrowing from moneylenders at 24% or 36% a year because the bank loan "takes too long". The Kisan Credit Card is supposed to fix exactly that: a revolving limit you can draw from for seeds, fertiliser, diesel and labour, at a fraction of the cost. It also covers animal husbandry and fisheries.
Here's how it works, what it really costs, and how to apply so your file doesn't sit in the branch for weeks.
Quick facts: Kisan Credit Card
| Item | Details |
|---|---|
| Official portal | Your bank's KCC page, Jan Samarth (jansamarth.in), PM-Kisan portal for the simplified form |
| Helpline | Your bank branch; banking ombudsman through cms.rbi.org.in for complaints |
| Fee | Processing and inspection charges waived for KCC limits up to ₹3 lakh, as per government and IBA guidance |
| Deadline | None; apply any time, ideally before the sowing season |
| Documents | Aadhaar, land records (khatauni, 7/12, jamabandi or pahani), photo, sowing details, lease or tenancy papers for tenant farmers |
| Interest | 7% on short-term crop loans up to the subvention limit (raised to ₹5 lakh in 2025-26 per PIB); 3% prompt repayment incentive brings it to 4% |
| Collateral | Not needed up to ₹2 lakh, per RBI's limit for agricultural loans |
| Validity | Usually five years, with yearly review |
Who can get a KCC?
• Farmers who own and cultivate land
• Tenant farmers, oral lessees and sharecroppers
• Self-help groups or joint liability groups of farmers
• Farmers in animal husbandry (dairy, poultry, goat rearing) and fisheries
If you're a tenant without papers, ask your bank about the joint liability group route. It's made for exactly this.
What does the KCC actually cost?
Under the government's Modified Interest Subvention Scheme, banks charge 7% a year on short-term crop loans up to the limit covered by the scheme. Repay on time, within the due date for that crop, and you get a 3% prompt repayment incentive. Your effective cost is 4%. Miss the date and you pay the normal rate on that amount.
In 2025-26 the government raised the crop loan limit under this scheme from ₹3 lakh to ₹5 lakh, and the collateral-free limit from ₹1.6 lakh to ₹2 lakh, according to a PIB release. Still, ask your branch to confirm in writing how much of your own limit gets the 7% and 4% rate.
How the limit is worked out
Your limit is based on the scale of finance for your crop in your district (set by the district technical committee), multiplied by the area you grow, plus a margin for post-harvest and household needs, farm maintenance and crop insurance. The limit usually rises by around 10% each year for five years, so you don't need to reapply every season.
How to apply for a KCC, step by step
1. Pick your bank. Go to the bank where you have a savings account, ideally the one in your village or block service area.
2. Get the form. Take the KCC form at the branch, download it from the bank's website, or apply online through the bank's app or Jan Samarth.
3. PM-Kisan farmer? Use the simple one-page KCC form available on the PM-Kisan portal. Your land and identity details are already verified for PM-Kisan, which makes things quicker.
4. Fill in details. Land holding, crops you grow each season, area and any existing loans.
5. Attach documents. Aadhaar, land records, photo and any lease papers.
6. Submit and get an acknowledgement. Ask for a dated receipt.
7. Field check. The bank may verify land and crops.
8. Sanction and card. Once sanctioned, you get a RuPay KCC card and can withdraw at ATMs or pay at shops.
RBI's guidance asks banks to decide on KCC applications within a set time after a complete application, commonly cited as 14 days. If your bank sits on it, complain.
Using your KCC well
• Draw only what you need, when you need it. Interest runs on what you've used, not the full limit.
• Repay right after harvest, before the due date, to keep the 4% rate.
• Keep the account active. Deposit sale proceeds into it.
• Crop insurance under PMFBY may be linked to your KCC. Check the premium and claim rules with your bank.
Common problems and fixes
| Problem | Likely reason | What to do |
|---|---|---|
| Bank asks for collateral below ₹2 lakh | Branch not following RBI's limit | Point to RBI's collateral-free limit; complain if refused |
| Land record rejected | Name or area mismatch | Fix the land record first (mutation or correction) |
| No reply for weeks | File stuck | Write to the branch manager, then the bank's grievance cell |
| Charged processing fee | Limit up to ₹3 lakh should be fee-free | Ask for a refund in writing |
| Card blocked | Overdue loan | Repay or restructure, then ask to reactivate |
A real-life example
Ravi, a farmer in Vidisha with 3 acres of soybean and wheat, applied with his B-1 and khasra and a PM-Kisan-linked Aadhaar. The bank sanctioned a limit based on the district's scale of finance. He drew money for seeds and fertiliser, repaid after the soybean harvest before the due date and paid about 4%. The same year, his neighbour borrowed from a trader at 2% a month. That's 24% a year.
Documents checklist
☐ Aadhaar card linked to mobile
☐ Land record (khatauni, 7/12, jamabandi, pahani or B-1)
☐ Passport-size photo
☐ Crop and area details for each season
☐ Lease or tenancy papers, if you're a tenant farmer
☐ Bank passbook
Fix your land record first
Most KCC delays come from land papers. Use our guides to check and fix yours: how to download your ROR land record, the Farmer ID under AgriStack and our check on your free credit report.
Where to complain
If the bank refuses without reason or delays, write to the branch, then the bank's grievance cell. If there's no fix in 30 days, file with the RBI's Integrated Ombudsman at cms.rbi.org.in. You can also raise it at the district lead bank meeting through your MP or MLA. Find them on NetaSampark.
KCC for dairy, poultry and fish farmers
You don't need farmland to get a KCC. Since 2019, the scheme also covers animal husbandry and fisheries for working capital: feed, medicines, labour, electricity and pond maintenance. Dairy farmers, poultry and goat rearers and fish farmers can apply with proof of the activity, like cattle ownership, a pond lease or a cooperative membership. The interest subvention applies here too, within the overall limit. If you do both farming and dairy, ask the bank to cover both in one card.
RuPay card safety
Your KCC comes as a RuPay debit card. Treat it like any ATM card: never share the PIN or OTP, and block it at once if lost. Fraudsters target farmers around loan season with "KCC renewal" calls. Banks don't ask for OTPs on calls.
Final reminder
Apply for your KCC before the sowing season rush, with clean land records. Draw only what you need, and always repay before the due date to keep your interest at 4%.
Frequently asked questions
What is the interest rate on a Kisan Credit Card?
7% a year on crop loans up to the subvention limit. If you repay on time, the 3% incentive makes it an effective 4%.
Do I need collateral for a KCC?
Not for loans up to ₹2 lakh, per RBI's limit for agricultural loans.
Can tenant farmers get a KCC?
Yes. Tenant farmers, sharecroppers and oral lessees can apply, often through joint liability groups.
Can PM-Kisan farmers apply more easily?
Yes. There's a simple one-page form for PM-Kisan beneficiaries, available on the PM-Kisan portal and at banks.
How long is a KCC valid?
Usually five years, with a yearly review of the limit.
Sources
• PIB press release on KCC and interest subvention