
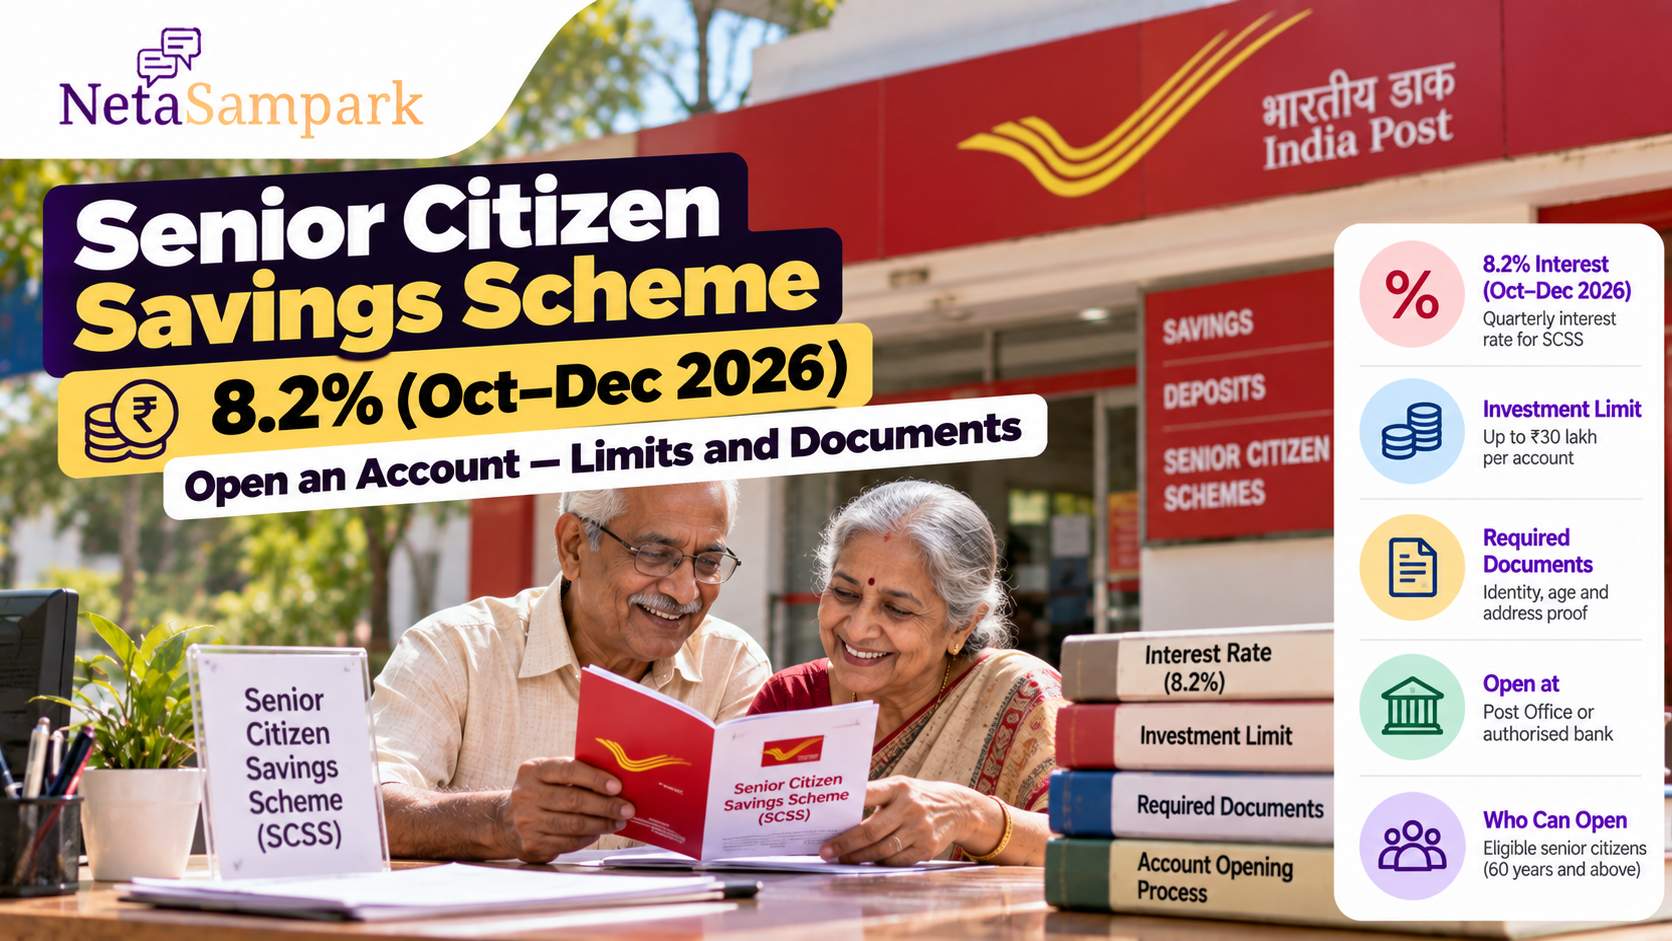
Senior Citizen Savings Scheme at 8.2% (Oct–Dec 2026): Open an Account — Limits and Documents
The Senior Citizens Savings Scheme (SCSS) continues to offer an 8.2% annual interest rate for October–December 2026. The Department of Economic Affairs confirmed on 30 September 2026 that small-savings rates for the third quarter of FY 2026–27 will remain unchanged from the previous quarter. DEA
For eligible senior citizens, SCSS offers a government-backed savings option with quarterly interest payments, a five-year maturity period and a maximum investment limit of ₹30 lakh. India Post
SCSS Interest Rate for October–December 2026
The SCSS rate for the current quarter is:
8.2% per annum
| Period | SCSS interest rate |
|---|---|
| April–June 2026 | 8.2% |
| July–September 2026 | 8.2% |
| October–December 2026 | 8.2% |
The government has kept all small-savings rates unchanged for Q3 FY 2026–27. DEA
Interest under SCSS is paid quarterly. It is not automatically reinvested into the SCSS account to earn further SCSS interest. Central Bank of India
How Much Interest Can ₹30 Lakh Generate?
At 8.2% per annum:
₹30,00,000 × 8.2% = ₹2,46,000 per year
That works out to approximately:
₹61,500 per quarter
This is a simple illustration based on the 8.2% annual rate; actual credit timing follows the SCSS payment rules.
For comparison:
| Deposit | Approx. annual interest at 8.2% | Approx. quarterly interest |
|---|---|---|
| ₹5 lakh | ₹41,000 | ₹10,250 |
| ₹10 lakh | ₹82,000 | ₹20,500 |
| ₹20 lakh | ₹1,64,000 | ₹41,000 |
| ₹30 lakh | ₹2,46,000 | ₹61,500 |
The interest is taxable according to the applicable income-tax rules.
Who Can Open an SCSS Account?
The basic eligibility is:
1. Senior citizens aged 60 or above
An individual who has attained 60 years of age can open an SCSS account.
2. Retired civilian employees aged 55–60
A person who has retired on superannuation or otherwise and is 55 or older but below 60 can qualify, subject to the scheme's conditions relating to retirement benefits and the prescribed time for making the investment. India Post's current customer material specifies investment within three months of receiving retirement benefits. India Post
3. Retired Defence personnel
Retired Defence Services personnel can qualify from age 50, subject to the applicable conditions. Central Bank of India
The special eligibility provisions for people below 60 are tied to retirement and the prescribed investment period, so simply being 55 or 50 is not enough by itself.
How Much Can You Invest?
The current maximum is:
₹30 lakh per individual
The minimum deposit is:
₹1,000
Deposits are made in multiples of ₹1,000, subject to the overall ₹30 lakh limit. The ₹30 lakh ceiling applies to the aggregate balance across an individual's SCSS accounts, rather than providing a separate ₹30 lakh limit for every account. India Post
The maximum was increased from ₹15 lakh to ₹30 lakh in 2023. India Post
Can a Couple Invest ₹60 Lakh?
Potentially, yes — if both spouses independently qualify and each opens an account in their own name.
The ₹30 lakh limit applies to the individual account holder's SCSS investment. A joint SCSS account can be opened with the spouse only, and the entire deposit in such a joint account is attributed to the first account holder for the scheme's limit. Central Bank of India
Therefore, couples should not assume that adding a spouse as a joint holder automatically creates another ₹30 lakh investment limit.
Where Can You Open an SCSS Account?
SCSS accounts can be opened through:
- Post Offices
- Authorised banks offering the scheme
India Post's customer guide specifically states that an SCSS account can be opened at a post office. India Post
Before visiting, check with the particular branch whether it handles SCSS account opening and what its current document requirements are.
Documents Required to Open SCSS
India Post's customer material lists the following basic documents:
- Two passport-size photographs
- Aadhaar card
- PAN card
- Retirement certificate, where applicable for eligible retirees below 60
- Proof relating to retirement benefits, where applicable India Post
The SCSS application also requires KYC and address/identity information. The scheme rules provide for accepted identity and address documents, including documents such as a passport, driving licence and voter ID, subject to the applicable KYC requirements. India Post
If you are opening the account after retirement before age 60
Keep additional retirement-related documents ready, including:
- Retirement certificate/employer certificate
- Proof of retirement
- Proof showing receipt/disbursement of retirement benefits
- Details of the retirement benefit being invested
What If You Invest More Than ₹10 Lakh?
India Post's customer guidance states that when investing more than ₹10 lakh, additional documents may be requested to establish the source of the funds.
Examples include:
- Bank/post-office statement showing the source of income
- Income-tax returns filed during the previous three years
- Property-sale documents
- Gift records
- Will or letters of administration
- Heir certificates
- Other official documents establishing the source of funds India Post
So if you are planning to invest ₹20 lakh or ₹30 lakh, carry supporting source-of-funds documents rather than arriving with only your Aadhaar and PAN.
How Long Does an SCSS Account Run?
The standard maturity period is:
5 years
At the end of five years, you can close the account and receive the deposit according to the scheme rules. Indian Kanoon
You can also extend the account for a further three-year block.
The 2023 amendment allows extensions in successive three-year blocks, subject to the prescribed application process. TaxGuru
What Happens If You Extend the Account?
An extension is not simply an automatic continuation of the original interest rate.
For an extended account, the applicable SCSS rate is the rate in force on the relevant maturity date. Central Bank of India
This means an account opened at 8.2% does not guarantee that every future three-year extension will also earn 8.2%.
The rate for the extension depends on the rate applicable when the extension takes effect.
Can You Withdraw the Money Before Five Years?
Yes, premature closure is permitted subject to the applicable conditions and deductions.
The standard penalty structure is:
| When you close | Treatment |
|---|---|
| Before 1 year | Interest already paid can be recovered; no SCSS interest benefit for the period |
| After 1 year but before 2 years | 1.5% of deposit deducted |
| On/after 2 years | 1% of deposit deducted |
| Extended account closed within first year of extension | 1% deduction |
The scheme rules provide these premature-closure conditions. Indian Kanoon
So SCSS should not be treated like an ordinary savings account where the entire deposit can be withdrawn whenever you want without consequences.
How Is the Interest Paid?
SCSS interest is paid quarterly.
The scheme calculates interest from the date of deposit to the relevant quarterly payment date and subsequently pays interest on the quarterly schedule. Central Bank of India
For example, someone investing ₹10 lakh at 8.2% would have an annual interest amount of about ₹82,000, or approximately ₹20,500 per quarter.
If you do not withdraw the interest, it does not itself earn additional SCSS interest. Central Bank of India
Is SCSS Interest Tax-Free?
No.
SCSS interest is taxable income.
The tax treatment depends on your overall income, applicable tax regime and other circumstances.
For AY 2026–27, the Income Tax Department lists Section 80TTB, under which a resident senior citizen can claim a deduction of up to ₹50,000 on eligible interest from deposits with banks, post offices or cooperative banks, subject to the applicable conditions. Income Tax Department
Also note that deductions such as 80C are associated with the old tax regime; the Income Tax Department's current guidance states that Chapter VI-A deductions such as 80C and 80TTB cannot generally be claimed when the new tax regime is selected. Income Tax Department
Important distinction
8.2% interest does not mean 8.2% tax-free return.
Your post-tax return depends on your individual tax position.
Does SCSS Qualify for a Tax Deduction?
Investment under SCSS qualifies for the applicable Section 80C deduction, subject to the overall limits and tax-regime conditions. India Post's scheme information identifies SCSS investment as eligible for Section 80C treatment. India Post
However, this benefit should be considered alongside your chosen tax regime.
The new tax regime does not allow the normal Chapter VI-A deductions such as 80C. Income Tax Department
What If You Already Have an SCSS Account?
You don't necessarily need to open a new account simply because the October–December 2026 rate is 8.2%.
The key question is when your existing account was opened and whether it is still within its original or extended tenure.
SCSS rates are periodically notified by the government. The current notification keeps the rate at 8.2% for Q3 FY 2026–27. DEA
If your account is approaching maturity, check the applicable extension rules and the rate available on the maturity date before deciding what to do.
What If You Are Retiring at 56 or 57?
This is one situation where the timing of the investment matters.
A retired civilian employee between 55 and 60 can qualify under the special eligibility provision, but the investment must be made within the prescribed period after receiving retirement benefits and the required retirement documentation must be submitted. India Post
So if you have recently retired, don't simply wait until you turn 60 before checking SCSS eligibility.
Can You Open an SCSS Account Jointly?
Yes, but the joint account facility is restricted.
The account can be held jointly with the spouse only. The deposit is attributed to the first account holder for the purpose of the scheme's investment limit. Central Bank of India
A joint SCSS account with a friend, sibling or other unrelated person is not the normal permitted structure.
What Happens If the Account Holder Dies?
SCSS has specific provisions for death of the account holder.
The account can be closed and the deposit paid to the nominee or legal heirs according to the applicable rules. In certain circumstances, a surviving spouse who is a joint holder or sole nominee can continue the account if the spouse meets the scheme's eligibility conditions. Indian Kanoon
This is one reason it is important to complete the nomination details correctly when opening the account.
SCSS Account Opening Checklist
Before visiting the Post Office or authorised bank, prepare:
Personal documents
- Aadhaar
- PAN
- Two passport-size photographs
- Address/identity proof if required
- Bank account details
If recently retired
- Retirement certificate
- Proof of retirement benefits
- Proof of date of receipt/disbursement
- Employer certificate where required
If investing more than ₹10 lakh
- Bank/post-office statement
- Income-tax return records
- Property-sale documents, if applicable
- Gift/will/inheritance documents, if applicable
- Other source-of-funds evidence
Account setup
- SCSS application form
- Nomination details
- Joint-holder details, if applicable
- Deposit/payment instrument
Before You Deposit ₹30 Lakh
A large SCSS deposit is a five-year commitment unless you use the permitted premature-closure route.
Before depositing the maximum amount, check:
1. Do you actually need the quarterly income?
2. Will you need a substantial portion of the principal within five years?
3. What will your post-tax return be?
4. Are you already close to the ₹30 lakh SCSS limit across existing accounts?
5. Is the investment compatible with your overall retirement cash-flow needs?
6. Have you kept enough money outside SCSS for emergencies?
The 8.2% rate is a government-notified scheme rate, but the right amount to invest depends on your personal financial circumstances.
SCSS at 8.2%: Quick Facts
| Feature | Current rule |
|---|---|
| Interest rate | 8.2% p.a. for Oct–Dec 2026 |
| Interest payment | Quarterly |
| Minimum deposit | ₹1,000 |
| Maximum investment | ₹30 lakh per individual |
| Normal tenure | 5 years |
| Extension | 3-year blocks |
| Joint account | Spouse only |
| Main eligibility | 60+ |
| Special retirement eligibility | Civilian retirees 55–60; Defence retirees 50–60, subject to conditions |
| Basic documents | Aadhaar, PAN, photographs, KYC/address proof |
| Extra documents | Retirement/source-of-funds proof where applicable |
| Tax on interest | Taxable, subject to applicable tax rules |
The current rate and scheme limits are based on the government's small-savings notification and the applicable SCSS rules. DEA
The Bottom Line
For October–December 2026, SCSS continues at 8.2% per year, with a ₹30 lakh maximum investment limit, quarterly interest payments and a standard five-year maturity. DEA
If you are eligible and considering an account, keep your Aadhaar, PAN, photographs, KYC documents and retirement documents ready. If you plan to invest more than ₹10 lakh, also prepare documents that can establish the source of the money. India Post
And remember: 8.2% is the gross scheme interest rate, not a tax-free return. Check the applicable tax treatment and your own cash-flow requirements before committing a large amount to the five-year scheme.