
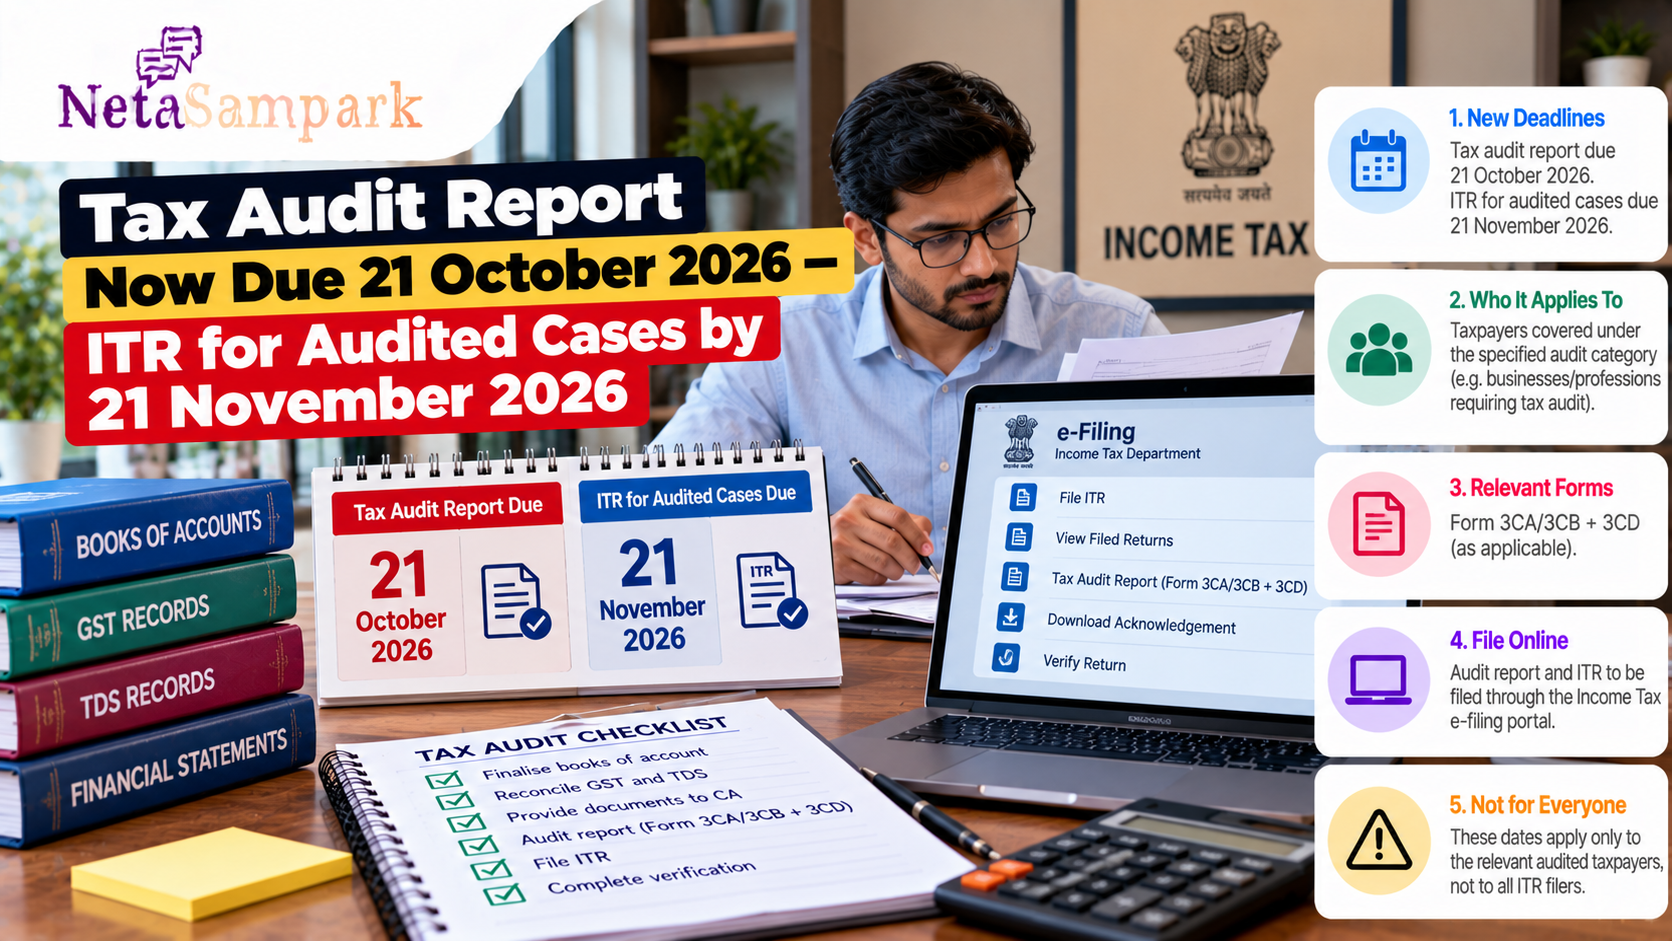
Tax Audit Report Now Due 21 October 2026 — ITR for Audited Cases by 21 November 2026
The Income Tax Department has extended the tax audit report deadline for AY 2026–27 to 21 October 2026 and the corresponding income-tax return deadline to 21 November 2026 for taxpayers covered by the specified audit category.
The extension was announced through CBDT Circular No. 07/2026 dated 28 September 2026. The earlier deadlines were 30 September 2026 for the audit report and 31 October 2026 for the ITR. Income Tax Department
If you run a business or profession that requires a tax audit, the two deadlines are linked: your audit report comes first, followed by the ITR.
What changed?
For the relevant taxpayers filing for AY 2026–27 (FY 2025–26):
| Compliance | Earlier deadline | Extended deadline |
|---|---|---|
| Tax Audit Report | 30 September 2026 | 21 October 2026 |
| Income Tax Return | 31 October 2026 | 21 November 2026 |
The extension applies specifically to the persons referred to in serial number 2 of the table under Explanation 2 to Section 139(1) of the Income-tax Act, 1961. Income Tax Department
This is not a blanket extension for every taxpayer.
Who needs to pay attention to these dates?
Broadly, these dates matter to taxpayers whose accounts are required to be audited under the tax-audit provisions.
The Income Tax Department's current guidance says tax audit requirements under Section 63 of the Income-tax Act, 2025—corresponding to Section 44AB of the earlier Act—include, among other cases:
- Businesses with turnover or gross receipts above ₹1 crore
- The threshold can go up to ₹10 crore where cash receipts and cash payments each remain within the specified 5% condition
- Professionals with gross receipts above ₹50 lakh
- Certain taxpayers who opt out of presumptive taxation and fall within the specified audit conditions
The exact applicability depends on your facts and the relevant tax provisions. Income Tax Department
So turnover alone should not be used to decide whether you need an audit.
What is a tax audit report?
A tax audit is an examination of specified accounts by a Chartered Accountant, followed by submission of the prescribed audit report and statement of particulars to the Income Tax Department.
For FY 2025–26 / AY 2026–27, the Income Tax Department says the existing forms under the Income-tax Act, 1961 continue to apply:
- Form 3CA + Form 3CD where the taxpayer's accounts are audited under another law
- Form 3CB + Form 3CD in other tax-audit cases
The report is furnished electronically through the income-tax e-filing system. Income Tax Department
Why the audit report must come before the ITR
The audit report is not simply an attachment that you can ignore while filing the return.
Your tax return needs to be prepared consistently with the financial information and particulars reported through the applicable audit forms.
That means businesses should not treat 21 October as merely their CA's deadline.
It is also the point by which the audited information should be ready for the subsequent ITR filing.
A practical timeline is:
Accounts finalised → CA audit → Form 3CA/3CB + 3CD filed → ITR prepared → ITR filed → Return verified
What should businesses do now?
1. Confirm whether tax audit applies
Don't assume that every business above ₹1 crore automatically needs an audit—or that every business below that figure is automatically outside the requirement.
Review:
- Turnover/gross receipts
- Cash receipts
- Cash payments
- Nature of business
- Whether accounts are audited under another law
- Presumptive-taxation provisions
- Whether you have opted out of a presumptive scheme
Ask your CA to confirm the applicable provision for FY 2025–26.
2. Give your CA complete records
Keep the following ready, as applicable:
- Books of account
- Sales and purchase records
- Bank statements
- Cash book
- GST records
- TDS records
- Fixed-asset details
- Loan statements
- Expense records
- Stock information
- Details of investments
- Details of related-party transactions
- Previous-year financial statements
- Tax payment information
The exact information required will depend on your business.
3. Reconcile GST and books
Differences between your books and GST filings can create questions during preparation of the audit report and ITR.
Check whether:
- Sales in the books reconcile with GST returns
- Input tax credit records are consistent
- Credit notes and debit notes are accounted for
- Turnover figures are correctly classified
- Outstanding receivables and payables are properly recorded
Don't wait until the last few days to discover a reconciliation issue.
4. Check the audit report on the e-filing portal
The tax-audit process involves electronic filing by the CA.
Make sure the relevant report has actually been submitted and that you can see the appropriate status on the income-tax portal.
A discussion with your CA is not the same as a successfully filed audit report.
Keep the filing acknowledgement and relevant records.
When should the ITR be filed?
For the taxpayers covered by the extension, the ITR deadline has moved from 31 October 2026 to 21 November 2026. Income Tax Department
That gives taxpayers roughly one month after the new audit-report deadline.
But don't interpret that as a reason to postpone the return preparation until 22 October.
Ideally, your CA should be preparing the ITR while finalising the audit so that the return can be filed soon after the audit report is completed.
Does this extension apply to salaried taxpayers?
Generally, no.
The 21 October and 21 November dates are connected to the category of taxpayers covered by the specified audit-related provision.
A salaried individual who is not subject to tax audit should not assume that these new dates apply to their ITR.
Taxpayers should check the due date applicable to their own category rather than relying on a general "ITR deadline extended" message.
What if I already filed the ITR?
If you already filed an ITR for AY 2026–27 before the extension, the extension does not mean you need to file the return again merely because the deadline has changed.
However, if your return belongs to a tax-audit category, ensure that the applicable audit-report compliance has also been completed.
If there is a genuine need to correct the return, discuss the appropriate revised-return or other available route with your tax professional.
Don't confuse tax audit with other audit reports
The Income Tax Department has several different audit/reporting requirements.
For example, charitable or religious trusts and certain institutions may have reporting requirements involving Forms 10B or 10BB. Those are not automatically covered by the same deadline simply because this article discusses tax-audit reports. Income Tax Department
Always identify the exact form and provision applicable to you.
What happens if you miss the new deadline?
Missing the extended deadline can have tax and compliance consequences.
Depending on the taxpayer and circumstances, delayed filing can result in:
- Late-filing consequences
- Additional tax/interest liabilities
- Possible penalties for audit-related non-compliance
- Problems with carrying forward certain losses
- Additional compliance work
The consequences depend on the specific provision and facts of the case.
Therefore, 21 October should be treated as the hard working deadline for completing the audit report—not as a date to start the audit process.
A practical October checklist
If your business is subject to tax audit, use this checklist:
☐ Confirm that tax audit applies to you
☐ Finalise books for FY 2025–26
☐ Reconcile bank, GST and TDS records
☐ Provide complete documents to your CA
☐ Review tax-audit particulars
☐ Ensure Form 3CA/3CB and Form 3CD are filed by 21 October
☐ Obtain/save the filing acknowledgement
☐ Finalise the ITR
☐ File the ITR by 21 November
☐ Complete ITR verification
The two dates to remember
For the relevant audited taxpayers filing AY 2026–27:
21 October 2026
Tax Audit Report deadline
21 November 2026
Income Tax Return deadline
The Income Tax Department has confirmed both extensions through its 29 September 2026 update referring to CBDT Circular No. 07/2026. Income Tax Department
Bottom line: If your business or profession falls under tax-audit requirements, don't wait for 21 October to begin. Get the books and reconciliations ready now, coordinate with your CA, ensure the audit report is actually filed by 21 October 2026, and then complete the corresponding ITR and verification by 21 November 2026.