
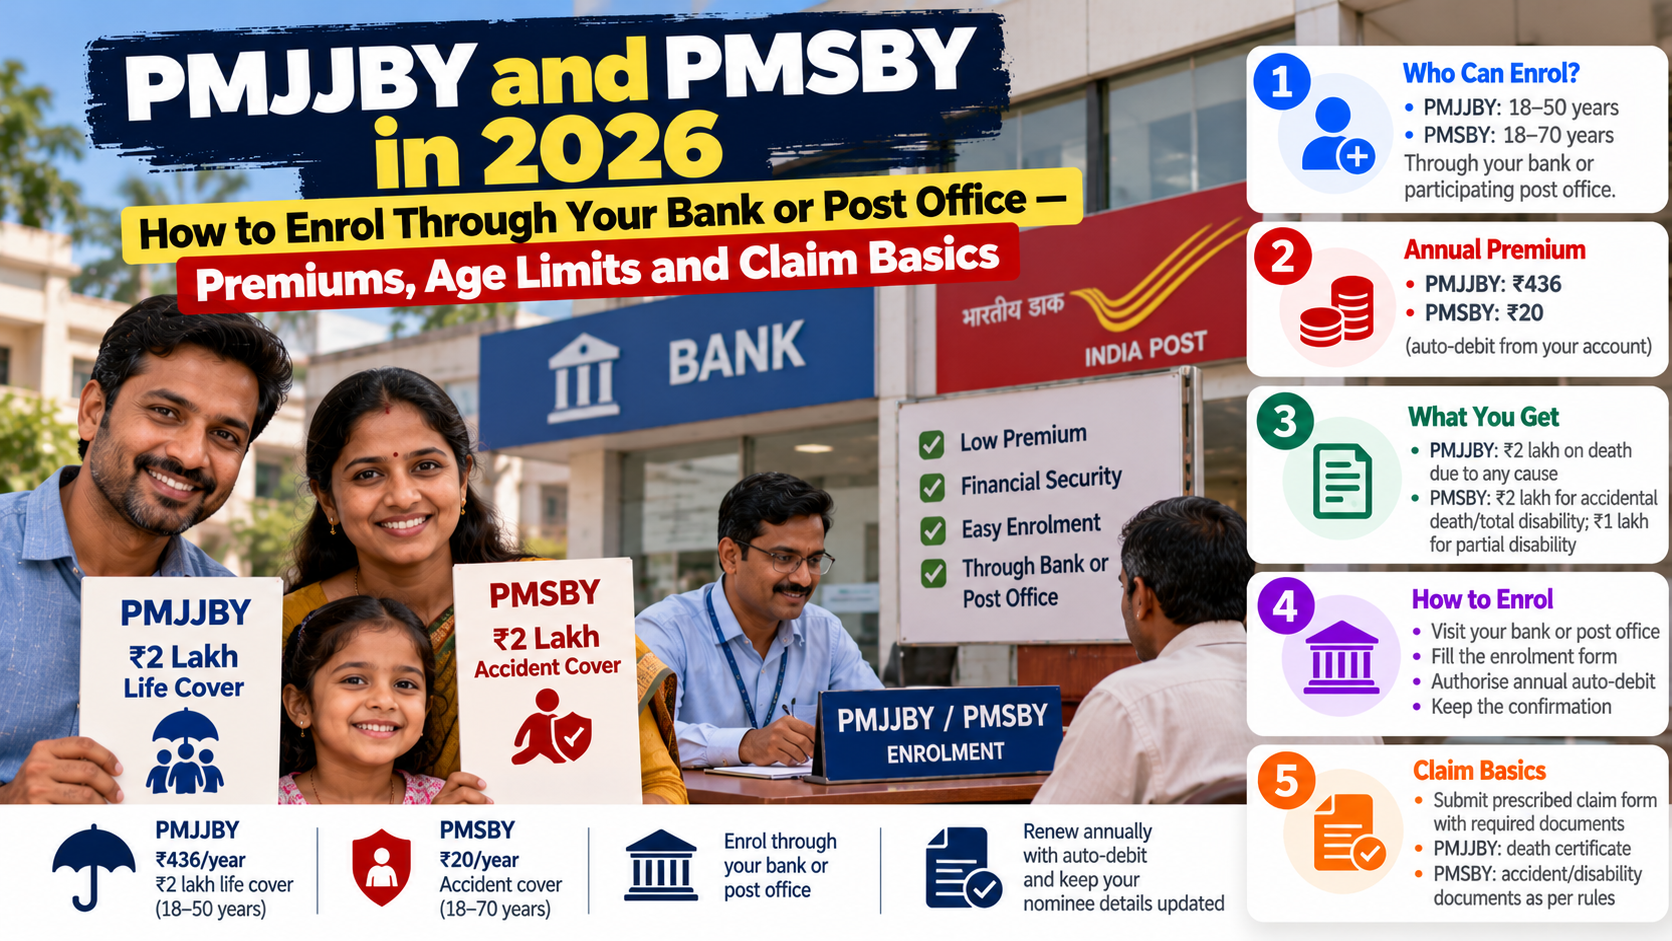
PMJJBY vs PMSBY: At a Glance
| Feature | PMJJBY | PMSBY |
|---|---|---|
| Full name | Pradhan Mantri Jeevan Jyoti Bima Yojana | Pradhan Mantri Suraksha Bima Yojana |
| Type of insurance | Life insurance | Personal accident insurance |
| Annual premium | ₹436 | ₹20 |
| Entry age | 18–50 years | 18–70 years |
| Main benefit | ₹2 lakh on death due to any cause, subject to policy terms | ₹2 lakh for accidental death or specified permanent total disability; ₹1 lakh for specified permanent partial disability |
| Cover period | 1 June–31 May | 1 June–31 May |
| Payment method | Bank/post office account auto-debit | Bank/post office account auto-debit |
| Renewal | Annual | Annual |
These are the published scheme terms for 2026. Confirm the applicable premium and terms with your participating bank or post office when enrolling. Sources: PMJJBY — Department of Financial Services and PMSBY — Department of Financial Services.
How to Enrol Through a Bank or Post Office
Both schemes are designed to be accessible through participating financial institutions.
- Visit your bank branch or participating post office, or check whether your bank offers digital enrolment.
- Ask for the PMJJBY, PMSBY or combined Jan Suraksha enrolment facility.
- Confirm that your savings account is eligible and that your age falls within the scheme's entry limit.
- Complete the prescribed enrolment and consent forms.
- Authorise the annual premium auto-debit.
- Keep the acknowledgement, insurance certificate or other confirmation issued by the institution.
- Check your account statement to confirm that the premium was debited and retain the confirmation for your records.
An individual holding several accounts can generally enrol under each scheme through only one eligible account per scheme. Duplicate enrolment does not create multiple benefits under the same scheme.
Official enrolment information is available through India Post's PMJJBY page and PMSBY page.
Important PMJJBY Rule: The First 30 Days
For a first-time PMJJBY enrolment or re-entry after leaving the scheme, a 30-day lien period applies to deaths from causes other than an accident. A claim for a non-accidental death during this period is not admissible under the scheme.
Do not confuse this provision with a blanket absence of cover during the first 30 days. The official scheme rules specifically distinguish accidental death from death due to other causes during the lien period.
Source: Official PMJJBY scheme details.
What Does PMSBY Cover—and What Does It Not Cover?
PMSBY is limited to specified outcomes resulting from an accident. It is not general health insurance and does not reimburse hospitalisation expenses simply because an accident occurred.
The published benefits are:
- ₹2 lakh: accidental death or specified permanent total disability.
- ₹1 lakh: specified permanent partial disability, such as the qualifying loss of sight in one eye or loss of use of one hand or foot.
The policy definition and medical evidence determine whether a particular injury qualifies. An injury that heals without a qualifying permanent disability does not automatically produce a claim payment.
PMSBY does not cover death by suicide. Accident-related claims must be supported by the documents required under the scheme.
Source: Official PMSBY scheme details.
How to Make a Claim
PMJJBY: Death claim
The nominee, appointee or eligible legal heir should approach the participating bank or post office through which the deceased was enrolled.
The claim process generally involves:
- Obtaining the prescribed PMJJBY claim form and discharge receipt.
- Providing the death certificate.
- Supplying the nominee's identity and bank-account details.
- Submitting any additional documents requested under the applicable claim procedure.
- Keeping an acknowledgement or claim reference.
The insurer checks whether the cover was active on the date of death and assesses the claim under the policy terms.
PMSBY: Accidental death or disability claim
The nominee or eligible claimant should contact the participating bank or post office promptly and obtain the prescribed PMSBY claim form.
Depending on the claim, documents may include:
- Death certificate for a death claim.
- FIR, panchnama or other police records where required by the circumstances.
- Post-mortem report for applicable accidental-death claims.
- Medical records and the prescribed disability certificate for a disability claim.
- The insured person's and claimant's identity details.
- Bank-account details for payment.
The exact documentation depends on the circumstances of the accident and the applicable claim procedure. Notify the institution promptly rather than waiting until the end of a presumed deadline.
Official claim guidance: PMJJBY claim documents and PMSBY claim documents.
Five Things to Check Every Year
- Renewal: Confirm that the scheme remains active for the new coverage year.
- Account balance: Maintain sufficient funds for the annual auto-debit.
- Nominee: Check that nomination details are accurate and up to date.
- Contact details: Keep your mobile number and other records current with the institution.
- Proof of cover: Retain the enrolment confirmation and annual debit entry.
Remember that the schemes renew annually; a deduction in a previous year is not, by itself, proof of current coverage.
Frequently Asked Questions
Can I enrol in both PMJJBY and PMSBY?
Yes, if you satisfy the eligibility requirements for each scheme. They provide different types of cover, and the benefits can complement one another.
Can I join after the annual renewal date?
Eligible individuals can generally join later, subject to the applicable rules and premium requirements. For PMJJBY, the applicable pro-rata premium and 30-day lien provisions must be checked; PMSBY's published rules allow delayed enrolment subject to payment of the annual premium.
Will the premium be refunded if I do not make a claim?
No. These are insurance schemes, not savings accounts. Premiums pay for the insurance cover during the policy period.
Does PMSBY pay for every accident?
No. Payment depends on whether the accident results in a covered death or qualifying permanent disability and whether the claim meets the policy conditions.
Can I rely on a bank debit alone as proof of coverage?
Keep the enrolment acknowledgement or insurance confirmation as well as the debit entry. If you are uncertain about the status of your cover, ask the bank or post office to verify it.
The Bottom Line
PMJJBY and PMSBY provide two different forms of low-cost financial protection: ₹2 lakh life cover under PMJJBY for death due to any cause, subject to the scheme's terms, and accident-related death and disability cover under PMSBY.
The published annual premiums are ₹436 and ₹20 respectively, with entry ages of 18–50 years for PMJJBY and 18–70 years for PMSBY. Enrol through a participating bank or post office, authorise auto-debit, check that your coverage is active and keep your nominee details current.
For the most reliable information, use the official Department of Financial Services PMJJBY page and PMSBY page, rather than relying solely on forwarded messages or third-party summaries.